AI vs. Human Debt Collectors has become a growing focus as debt collection quietly enters a new era of AI-driven transformation. Finance teams that were skeptical two years ago are now running side-by-side comparisons, and the numbers are starting to tell a clearer story. But “AI recovers more” is a headline that needs some unpacking because the real answer depends on debt age, account type, and how AI is actually being used.
Here’s what the data shows, and where human judgment still matters.
The Core Numbers
Recovery rates vary a lot depending on how old the debt is and what kind of debt it is. Fresh B2B debts under six months old can recover at 70% to 90%, while debts older than two years see recovery rates collapse. That decay curve is the single most important fact in collections: speed matters more than almost anything else.
This is where AI excels most. A human collector can handle about 80-120 accounts each day, while an AI collector can work with 1,000 accounts at the same time, following the same script for all communications.
Recovery-rate comparisons across published benchmarks tend to fall within a consistent range. One industry report puts traditional agency recovery at 20 to 30% over six months, against roughly 50% in 20 days for AI collection platforms. Another source citing PYMNTS Intelligence found that recovery rates on delinquent commercial accounts rise by an average of 15 to 22 percentage points when AI prioritization replaces aging-bucket segmentation.
Why AI Tends to Win on Speed and Reach, Not Persuasion
Artificial intelligence is simply a superior negotiator compared to humans. However, the data does not support this. The key reason for the superiority of AI in this domain, as one report states, is that the improvement in recovery rates is not due to AI being a better negotiator than human experts, but instead is a result of significant progress in coverage, as the AI system interacts with thousands of people at the same time. In contrast, a team of people can contact only a few hundred people in that time.
In other words, AI performs better than humans in the same way. It arrives before the collector, is more persistent, and uses more communication methods at once. These methods include email, SMS, and phone calls, and they can run different tactics simultaneously instead of waiting to deal with clients in priority order.
Where Human Collectors Still Hold an Edge
None of this means human collectors are obsolete. A few situations still favor a person on the line:
- High-value, relationship-sensitive accounts. A large enterprise client with a long-term contract often needs a human who can negotiate terms, not a script.
- Emotionally complicated consumer cases. Hardship situations, disputes, and cases nearing legal escalation usually need a person who can read tone and adjust in real time.
- Complex payment plan restructuring. AI can offer standard plans, but multi-variable negotiations still tend to go to experienced staff.
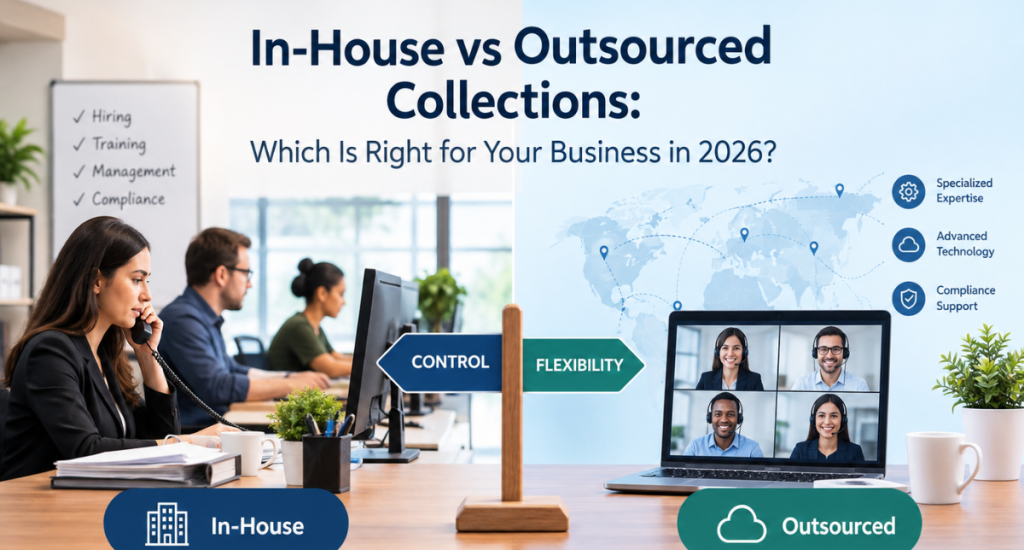
- Regarding the strongest operations in 2026, it is no longer a matter of choosing either AI or humans. The focus has drifted away from that. The emphasis is now on segmenting accounts by category: AI will handle high volume and initial processes, while human debt collectors will manage sensitive and more complex cases after the AI has initiated action.
AI vs. Human Debt Collectors: The Compliance Angle
This is where AI faces a major trust problem, and where leaders are already ahead of the curve. The volume of regulatory complaints is increasing substantially. The CFPB has handled around 207,800 debt collection complaints in 2024, nearly double the 109,900 recorded in 2023. Regulators have said there is no specific exemption for automation equipment because the AI system operates under the same conditions as FCC, Regulation F, TCPA, and UDAAP regulations.
This matters because a fast AI engine with poor compliance can expose the company to more liability than a slow human team. That is one reason collection agencies like Kollecta focus heavily on audit trails and rule enforcement. They do this in each conversation rather than treating compliance as a document that isn’t checked against actual calls. So if a financial team uses AI for compliance instead of spot-checking, it gets work done faster and avoids the risks of massive increases in contact volumes.
Cost Is Part of the Recovery Story Too
Recovery rate alone does not tell the full financial picture. Cost to collect matters just as much. Cost to collect drops 25 to 35% at organizations with mature AI collections deployments, driven by fewer low-value collector touches and faster resolution on high-risk accounts. Agency fee structures reinforce this gap further, since traditional agencies typically charge 25 to 50% of recovered amounts, compared to 5 to 15% success-based fees at most AI collection platforms.
So even when a human collector closes a similar percentage of accounts, the net amount a business keeps can look very different once fees are factored in.
AI vs. Human Debt Collectors: Who Actually Recovers More?
The answer is not simply that one approach always outperforms the other. AI collection systems can provide greater speed, consistency, and account coverage, while human collectors remain valuable for complex, high-stakes, and relationship-sensitive cases.
For many finance teams in 2026, the practical approach is a layered model: AI tools handle early-stage, high-volume outreach with appropriate compliance controls, while human collectors step in when an account requires judgment, negotiation, or empathy.